
What a time it’s been for Qualys. In the past six months alone, the company’s stock price has increased by a massive 83.7%, reaching $174.47 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Qualys, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Qualys Not Exciting?
We’re happy investors have made money, but we don’t have much confidence in Qualys. Here are three reasons why there are better opportunities than QLYS, plus one stock we’d rather own.
1. Weak ARR Points to Soft Demand
While reported revenue for a software company can include low-margin items like implementation fees, annual recurring revenue (ARR) is a sum of the next 12 months of contracted revenue purely from software subscriptions, or the high-margin, predictable revenue streams that make SaaS businesses so valuable.
Qualys’s ARR came in at $728.7 million in Q2, and over the last four quarters, its year-on-year growth averaged 10.3%. This performance was underwhelming and suggests that increasing competition is causing challenges in securing longer-term commitments. 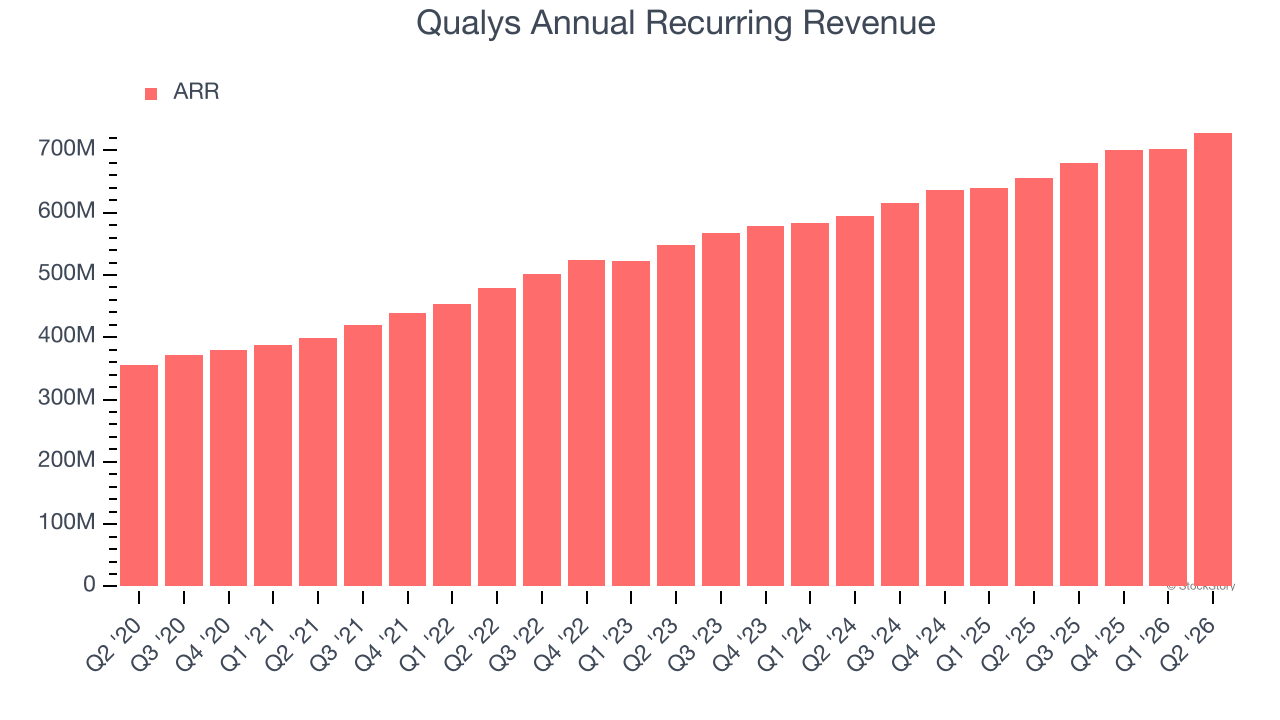
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Qualys’s revenue to rise by 8.9%, close to its 12.8% annualized growth for the past five years. This projection is underwhelming and suggests its newer products and services will not accelerate its top-line performance yet.
3. Operating Margin Rising, Profits Up
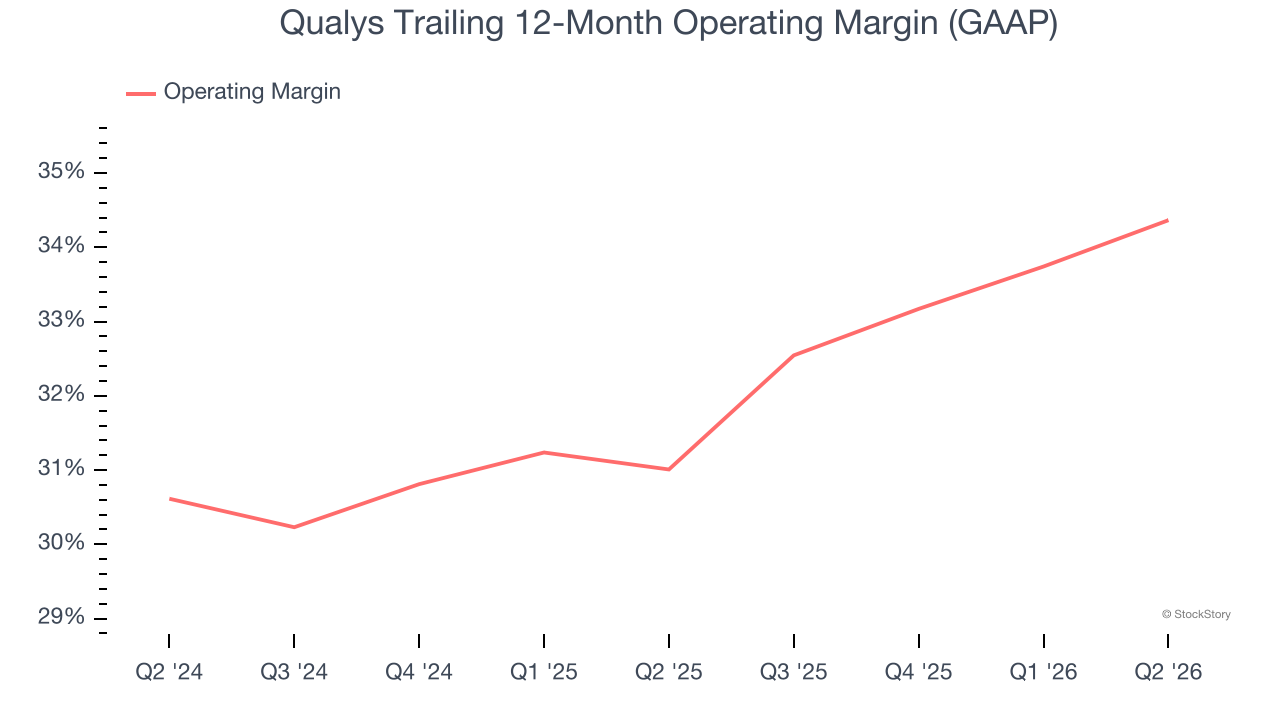
Many software businesses adjust their profits for stock-based compensation (SBC), but we prioritize GAAP operating margin because SBC is a real expense used to attract and retain engineering and sales talent. This is one of the best measures of profitability because it shows how much money a company takes home after developing, marketing, and selling its products.
Analyzing the trend in its profitability, Qualys’s operating margin rose by 3.4 percentage points over the last two years, as its sales growth gave it operating leverage. Its operating margin for the trailing 12 months was 34.4%.
Final Judgment
Qualys isn’t a terrible business, but it doesn’t pass our bar. After the recent surge, the stock trades at 6.9× forward price-to-sales (or $174.47 per share). Investors with a higher risk tolerance might like the company, but we don’t really see a big opportunity at the moment. We’re pretty confident there are superior stocks to buy right now. Let us point you toward the Amazon and PayPal of Latin America.
Stocks We Like More Than Qualys
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.